Money Eco: Budget / Expense

Screenshots
Details
- Rating
- 11.00 reviews
- Version
- 7.1.0
- Developer
- Apponance, Inc.
Analysis by Norviv
If you want to understand where your money goes without turning budgeting into a second job, Money Eco: Budget / Expense is a sensible place to start. I approached it as a first-time user would: looking for a quick way to record spending, see patterns, and make a more realistic plan for the next few weeks. It is a free finance app from Apponance, Inc., aimed at money management, expense tracking, and personal-finance visualisation.
My first impression was that its value depends less on complicated financial tools and more on whether you build a simple recording habit. That is important because an expense tracker can look useful on the first day and still become irrelevant if entering purchases feels like paperwork. Money Eco works best when I use it as a short daily check-in rather than an occasional attempt to reconstruct an entire month.
The app is available to a broad audience, with an Everyone content rating, and it has reached over ten thousand installs. Its average rating is 4.7 from around fifty ratings, which suggests a generally positive response, although that is still a relatively small group of opinions. I would treat those figures as encouraging rather than conclusive. The more useful question is whether its straightforward approach matches the way you personally handle money.
Getting from installation to a useful first budget
I start with the smallest setup that can answer a real question: a few everyday spending categories and one purchase I can record straight away. That keeps budgeting from becoming a design project, while showing whether the basic routine feels comfortable on my phone. Once that first entry is in place, I can see how a simple, consistent tracking habit leads into the choices and trade-offs involved in using the app over time.
What to expect when you open it
Money Eco is not the kind of finance product I would choose for complex investing, tax preparation, or detailed household accounting. Its focus is narrower and more practical: recording expenses, organising a personal budget, and turning those entries into visual reports. That narrower purpose is a strength for someone who feels overwhelmed by financial software, but it also means the app should be judged as a daily money-awareness tool rather than a complete financial command centre.
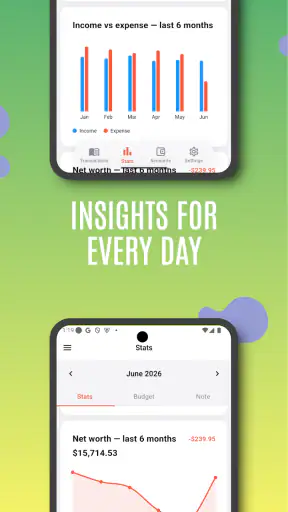
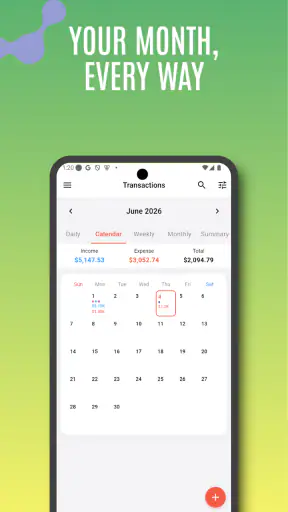
The most useful mental model is a three-part loop. I record what I spent, I group it in a way that makes sense to me, and I look back at the resulting picture before making the next decision. The visual side matters because a list of amounts can hide a pattern. Several small purchases may feel harmless individually, while a chart or summary can make their combined effect much easier to notice.
I would not install it expecting the app to automatically fix an untidy budget. The quality of the result depends on the consistency and clarity of the information I enter. If I record only rent and large bills but ignore snacks, transport, subscriptions, or cash purchases, the report may look neat while still giving me a misleading view of my habits.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
That is the first non-obvious trade-off: manual tracking gives me control over what is recorded, but it also makes omissions my responsibility. Someone who wants a hands-off experience connected to every account may prefer a different kind of finance app. Someone who wants to decide exactly what belongs in the record may appreciate this more deliberate approach.
Setting up without overcomplicating the categories
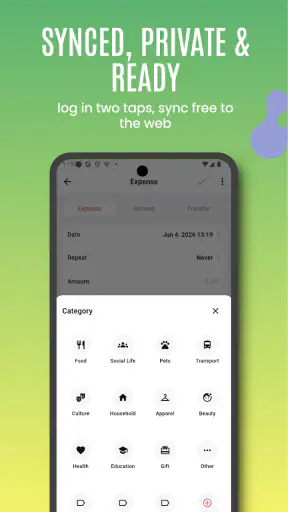
For a first setup, I recommend starting with the categories that answer an immediate question. Instead of trying to design a perfect financial system, I would begin with essentials such as housing, food, transport, and recurring bills, then add one or two flexible areas that reflect my actual life. The goal is to make the first report readable, not to catalogue every possible type of purchase.
This is where many new users create unnecessary friction. Too many categories make every entry feel like a decision, especially when a purchase could reasonably fit in several places. If I buy lunch while travelling, for example, I need a rule that I can apply quickly. I might place it under food every time, or under travel when the trip itself is the important context. Consistency is more valuable than theoretical precision.
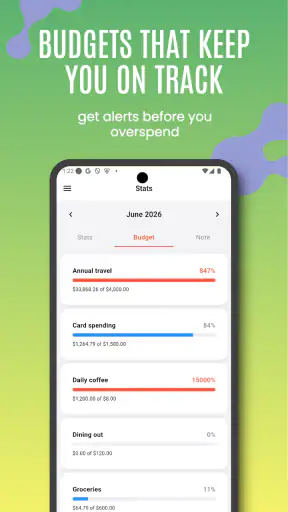
I also find it helpful to choose a realistic budget rather than an aspirational one. If my normal spending is higher than I would like, entering an unrealistically low target only creates a warning that I will ignore. A practical first budget should reflect what I can actually manage, leaving room to adjust after I see a complete spending pattern.
Money Eco becomes more useful when I treat the first setup as a draft. I do not need to get every category right before recording the first expense. I can begin with a small structure, notice which purchases do not fit comfortably, and refine the arrangement later. That approach gets me to useful feedback sooner and avoids spending an hour planning a system I may not enjoy using.
The first successful action: record one ordinary purchase
The quickest way to find out whether this app suits me is to record a purchase I made today, not an old transaction I have to remember vaguely. A coffee, a bus fare, or a grocery item is enough. I enter it carefully, place it in the category I have chosen, and then check how it affects the budget view or visual report. That small sequence is more informative than browsing every screen before using the app.
My definition of success is not simply seeing a number saved. It is understanding what the number means. After the first entry, I want to know whether the category is clear, whether the amount is easy to review, and whether the summary helps me make a decision. If I can answer, “How much room do I have left for this type of spending?” the app has already delivered a meaningful result.
A useful routine is to enter expenses at the moment I finish a purchase, or during a fixed evening check-in. The second option works well if I make only a handful of transactions and can remember them accurately. For a busy day with many small purchases, immediate entry is safer. Waiting until the weekend may turn a simple habit into detective work, especially when cash spending is involved.
One practical tip is to use the visual report as a review tool rather than staring at it after every transaction. A single coffee will not reveal much. A week of reasonably complete entries can show whether a category is growing faster than expected or whether a budget amount was unrealistic. The report becomes more valuable when it supports a small change, such as planning meals, reducing impulse purchases, or setting aside money before discretionary spending begins.
A realistic everyday routine
Imagine I am paid near the beginning of the month and want to avoid reaching the final week with no clear explanation for where the money went. I set up a few broad categories, record my fixed commitments, and then track flexible spending as the month develops. After several days, the report shows that food spending is not coming mainly from groceries but from frequent small purchases outside the home.
The useful response is not to panic or delete those entries. I can decide whether the category needs a separate distinction, whether the budget should be adjusted, or whether I want to change the habit. The app cannot make that judgement for me, but it can make the pattern visible. That is a better outcome than relying on a vague feeling that I am spending “too much.”
For a shared household, I would use it carefully. It may help one person keep a personal record or prepare for a conversation about recurring expenses, but I would not assume it replaces a coordinated family system. Everyone involved would need to agree on categories, timing, and who records which purchases. Without that agreement, the report could reflect only one person’s side of the household finances.
Where new users may become confused
The first common confusion is the difference between a transaction record and a budget plan. Recording that I spent money tells me what happened. Setting a budget expresses what I want to happen. Those are related but not identical. If the report looks disappointing, I should first check whether the issue is incomplete entries, unsuitable categories, or a budget that was too strict from the beginning.
A second source of confusion is the temptation to interpret a visual summary as a complete financial diagnosis. A chart can organise the information I entered, but it cannot know about an expense I forgot, a bill due later, or money held in another place unless I include it in the system. I use the visualisation to spot patterns, not as proof that every part of my financial life has been captured.
A third issue is category drift. If I classify similar purchases differently from week to week, comparisons become less useful. This can happen when I create new categories whenever an entry feels slightly unusual. I get a more detailed-looking report, but the detail may be too fragmented to guide a decision. I prefer to keep a short personal rule for borderline purchases and follow it consistently.
There can also be a difference between what I want to see and what is easy to maintain. Detailed tracking may sound attractive, yet the most valuable system is usually the one I will still use after the novelty fades. If entering every tiny transaction becomes irritating, I would simplify the categories before abandoning the habit. A less detailed record that is complete is more useful than a perfect-looking record with missing days.
Using the reports to make one decision at a time
The visual reporting is most helpful when I attach it to a question. Instead of opening the report passively, I might ask whether transport is rising, whether discretionary purchases are crowding out essentials, or whether a recurring bill has been included in the right period. A focused question turns a collection of figures into an action plan.
One advanced but simple workflow is to review the report at the same point in each spending cycle, then write down one adjustment for the next cycle. I might lower a flexible category slightly, move a recurring expense into a more appropriate group, or create a small buffer for irregular purchases. Making one change keeps the process manageable and makes it easier to tell which adjustment helped.
Another useful approach is to separate observation from judgement. During the first review, I identify what actually happened. During the second, I decide what I want to change. This prevents me from editing entries merely because I dislike the result. Accurate records can be uncomfortable, but they are much more useful than records adjusted to make the report look better.
I would also avoid comparing categories that do not have the same level of completeness. If I recorded every grocery purchase but forgot several cash purchases, the apparent difference between food and entertainment may be meaningless. Before drawing a conclusion, I ask whether I have tracked both areas with similar care.
How it compares with familiar alternatives
The usual alternative is a notes app or spreadsheet. Those options can be flexible and may suit someone who wants complete control over formulas and layout. Money Eco has a clearer finance-specific purpose, so I would choose it when I want the app to organise expense tracking and present the results visually without building the structure myself. A spreadsheet remains better for users who enjoy custom calculations or need a highly individual reporting system.
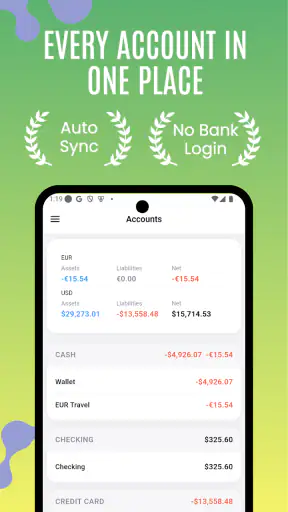
Another alternative is a banking app. Banking tools are convenient for checking balances and reviewing transactions connected to an account, but they may not match the way I want to think about personal spending. A dedicated tracker can be useful when I want a separate budgeting view, when I use more than one payment method, or when I prefer to enter information intentionally rather than simply browse a bank feed.
At the other end are full-featured finance platforms that combine account connections, shared planning, reminders, debt tools, and broader financial management. Those can be better for a household with complicated finances or someone who wants extensive automation. Money Eco is more appealing when I want a focused, approachable record of spending and do not need a large ecosystem around it.
The trade-off is clear: the simpler the workflow, the less likely I am to feel buried in options, but the more I may need to supply and maintain myself. I would recommend it to a beginner who wants a visual budget and is willing to build a modest manual habit. I would skip it in favour of a more comprehensive service if automatic account-level management is the main reason I am looking for a finance app.
Practical details before committing to the habit
The app is free to download, while in-app purchases range from under a dollar to around fifteen dollars per item. I would check the purchase prompts carefully and decide whether the free experience already covers my needs before paying for anything. For a first-time user, the sensible approach is to test the basic routine first: create a manageable structure, enter ordinary expenses, and review the report over several days.
The current version is 7.1.0, and the app requires Android 7.0 or later. That makes device compatibility worth checking before installation, particularly if I use an older phone. I would also remember that the app is listed as a finance tool, not as professional financial advice. Its reports can support better awareness, but decisions about debt, investments, taxes, or major commitments deserve information beyond a spending chart.
Because the developer is Apponance, Inc., I would look at the app’s current on-device prompts and settings during setup rather than assuming that every phone will present the same experience. In practical terms, I want to know where my entries appear, how easily I can correct a mistake, and whether the categories remain understandable after I have used the app for a while. Those checks tell me more about long-term suitability than the first attractive summary screen.
Privacy-conscious users should also decide how much financial detail they are comfortable entering into any budgeting product. I would begin with the minimum information needed to test the workflow and avoid adding sensitive notes that do not improve the budget. That is not a criticism specific to Money Eco; it is simply a sensible boundary for any app that stores personal spending information.
Who will benefit, and who should choose something else
I see Money Eco as a good fit for someone making a first serious attempt at budgeting, a student learning to manage regular expenses, or a person who wants a visual explanation for why the month feels tighter than expected. It can also suit a user who has tried spreadsheets but found them too open-ended. The combination of categories, expense records, and visual feedback gives the process a clear direction without requiring advanced financial knowledge.
I would be more cautious about recommending it to someone who refuses manual entry, needs several people to update one shared plan, or expects detailed forecasting across accounts and investments. It may also be a poor match for a person who becomes anxious when monitoring every purchase. In that case, a simpler weekly allowance method or a bank-based overview might encourage healthier use than constant transaction-level checking.
My strongest recommendation is to start small. Do not wait until you have a complete history. Add a few meaningful categories, record the next ordinary purchase, and use the first report to answer one practical question. If that process feels clear after several days, expand it gradually. If it feels like administrative work even with a simple setup, the problem is probably not a missing feature; this may simply not be the right style of money management for you.
Overall, I find Money Eco: Budget / Expense most convincing as a gentle entry point into deliberate spending. It does not remove the need for honest records or thoughtful decisions, and its focused design will not satisfy everyone looking for a full financial suite. But for a first-time user who wants to move from vague concern to a visible, actionable picture of everyday expenses, it offers a practical path: record one purchase, keep the categories consistent, review the pattern, and make one realistic change.
That is the kind of progress I would want from a budgeting app. Not a complicated financial makeover on the first day, but a small success that makes the next decision easier. If you are comfortable taking responsibility for the entries and want reports that turn them into an understandable spending picture, this free finance app is worth trying. If automation and advanced household management matter more than simplicity, I would look elsewhere.
Frequently Asked Questions
01What is Money Eco: Budget / Expense used for?
Money Eco: Budget / Expense is a personal finance app designed to help you record income, track daily spending, organize transactions into categories, and understand where your money goes. After reviewing its main features, it appears most useful for people who want a simple overview of their finances without relying on spreadsheets. It can also support budgeting habits by making recurring expenses and spending patterns easier to monitor.
02Can I create a personal budget with Money Eco: Budget / Expense?
Yes, the app is intended to help users plan and manage budgets by setting spending limits and comparing them with recorded expenses. You can generally organize your finances by categories such as food, transportation, bills, shopping, and entertainment. This makes it easier to identify categories where you are overspending. However, the exact budgeting tools and available limits may depend on the app version and whether certain features require a premium upgrade.
03Does Money Eco: Budget / Expense connect directly to my bank account?
Users should check the app’s current description and permissions before assuming that automatic bank synchronization is available. Many expense trackers focus on manual transaction entry, while others may offer imports or financial-account connections in selected regions. If Money Eco: Budget / Expense requires manual recording, it gives you more control over what is stored but also demands consistency. Avoid entering sensitive banking credentials unless the connection is clearly official and securely explained.
04Is Money Eco: Budget / Expense free to download and use?
The application may be available to download at no initial cost, but some functions can be limited by advertisements, in-app purchases, or a paid version. Before installing, review the store listing for details about subscriptions, premium budgeting tools, backup options, export features, and advertising. The free version may be sufficient for basic expense tracking, while users who need advanced reports or additional customization should verify the current pricing first.
05Is my financial information safe when using Money Eco: Budget / Expense?
Because the app handles personal financial information, privacy and security should be considered before entering detailed data. Review its privacy policy, requested permissions, storage method, backup options, and whether information is shared with third parties. Use a strong device passcode and enable any available app lock or biometric protection. It is also wise to avoid storing unnecessary account numbers, card details, or other highly sensitive information in a budgeting app.


